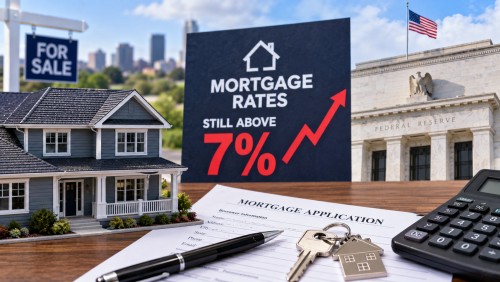
Homebuyers in the United States are facing increased financial pressure as mortgage rates persist above 7%, following the Federal Reserve’s recent decision to raise its target interest-rate range to 3.75%–4%. This increase is part of the Fed’s ongoing effort to combat inflation, which remains well above its 2% target. The higher mortgage rates mean that borrowing costs for prospective homebuyers have risen significantly, affecting their purchasing power and potentially delaying homeownership plans.
Despite the Federal Reserve’s rate hike, mortgage rates aren’t solely determined by the Fed’s policy decisions. Instead, they are influenced by a combination of factors including financial markets, inflation expectations, and investor demand. As of September 17, 2026, the average 30-year mortgage rate reached 7.37%, up from 5.75% in March. Similarly, the average 15-year mortgage rate was 6.62%. These higher rates translate into increased monthly payments for many potential buyers.
For those looking to purchase a home, there are still opportunities to secure rates below the national average. Factors such as credit score, down payment size, lender choice, and loan terms play a crucial role in determining the final mortgage rate. Additionally, buyers might consider paying mortgage points upfront to lower their interest rate, although this will raise closing costs. Another option is opting for adjustable-rate mortgages, which offer lower initial rates but carry the risk of rate increases after the initial period.
The refinancing landscape has also been affected, with the average 30-year refinance rate at 7.41% and the 15-year refinance rate at 6.75%. For homeowners with existing mortgages at much lower rates, refinancing is less attractive unless the savings outweigh the costs involved. This situation may prompt homeowners to weigh their options carefully before making refinancing decisions.
Looking ahead, the trajectory of mortgage rates will largely depend on broader economic factors, including inflation trends, financial market conditions, and expectations regarding further Federal Reserve policy actions. While some may hope for a decrease in rates, there is no certainty that waiting will lead to more favorable borrowing terms.